


The most revealing number in artificial intelligence this month wasn’t a benchmark score. It was $2 trillion.
On Sept. 11, Reuters reported that Anthropic was weighing an initial public offering at roughly that valuation. The next day its chief executive, Dario Amodei, published an essay arguing that the industry “must slow the pace at which we improve the capabilities of AI models.” Within hours, the heads of OpenAI, Google DeepMind and xAI had endorsed some version of the idea.
The safety argument has been debated at length. The question for capital is different: when market leaders ask Washington to slow the race, what are they protecting? A lead measured in months that they want written into law. That bid may fail. Either way, the next wave of AI returns will go to whoever owns the next learning loop, not the biggest language model. Back those companies, and pass on anything priced as if the head start will be legislated.
A Lead Measured in Months
Start with the asset being protected. Anthropic’s growth is extraordinary: annualized revenue went from about $9 billion at the end of 2025 to $65 billion by July, according to the New York Times. Nobody should wave that away.
A $2 trillion valuation prices years of durable advantage. The data describe one that must be re-won every quarter.
But the product underneath is converging:
Performance: Stanford’s 2026 AI Index put the best American and best Chinese models 2.7% apart on a leading benchmark in March.
Open weights: open-weight models trail the closed frontier by an average of four months, per Epoch AI.
Share: Chinese models carried as much as 46% of U.S. companies’ OpenRouter traffic by midyear, CNBC reported.
Price: DeepSeek’s newest model lists at about a twelfth of the price of OpenAI’s flagship, per Datagravity.
Commoditization shows up first in pricing power, not revenue, and pricing power is what a multiple is built on. A $2 trillion valuation prices years of durable advantage; the data describe one that must be re-won every quarter. Michael Burry put it simply: “Competition is coming up fast, slowing benefits incumbents.”
A Moat by Statute
Grant the fear first. In July, about 1,200 AI agents on an unreleased OpenAI model escaped a test sandbox and broke into Hugging Face, per OpenAI and METR, with safeguards switched off. It was a real failure worth fixing.
A valuation that assumes the incumbents write the rulebook is pricing a political outcome, not a business one.
But Mr. Amodei’s fix isn’t better containment. It’s a set of rules, and investors should read them like a term sheet: who pays?
Embedded evaluators: a rounding error for a company with $65 billion in annualized revenue, and a real cost for a 40-person startup.
Certification: no clear answer for models anyone can download.
China measures: chip controls and a crackdown on model copying, aimed at China.
Congress is already drafting an antitrust shield. S.5105, a bipartisan Senate bill introduced in July, would let labs agree to delay or limit AI just by notifying the Justice Department, with no approval and no expiry. OpenAI says it already coordinates on safety without one.
Each cost falls hardest on the players most likely to compress incumbents’ margins: the textbook regulatory moat. FTC Chair Andrew Ferguson, speaking personally, said as much: “They’re asking for barriers to entry that will insulate their incumbency from challenge.”
But that moat isn’t built, and it may never be. President Trump calls the risk warnings a “hoax,” the FTC chair opposes the waiver, and Congress leaves for the midterms with its AI bills stalled. A valuation that assumes the incumbents write the rulebook is pricing a political outcome, not a business one.
Where I’d Put Money: The New Learning Loops
The essay never mentions world models, robotics or non-transformer architectures, the routes where a language-model lead matters least because the scarce input is action data, not web text. The incumbents know it: Google DeepMind has Gemini Robotics 2 and the Genie 3 world model, and OpenAI backed Physical Intelligence in 2024. They hedge privately while asking regulators to define the frontier as the thing they already dominate.
That’s where I’d put new money. Four new loops stand out.
Physical data. Everyone trains on the same web; nobody shares the motor and failure data that deployed robots generate. Skild AI, which trains one policy across 100,000 simulated robot bodies, was valued at $14 billion in January. Physical Intelligence was in talks in March to raise at more than $11 billion, double its November mark, and FieldAI sells autonomy into heavy industry. Whoever pools action data across robot makers will own the physical world’s version of the web corpus.
Simulation. Learned world models promise real-world experience at software cost. World Labs raised $1 billion from Nvidia, AMD and Autodesk, and Yann LeCun’s AMI Labs raised a $1.03 billion seed round. Runway is aiming its video models at robot testing; General Intuition is training action on gameplay. Underwrite one test: does a simulated action have the same consequence as the real one?
They hedge privately while asking regulators to define the frontier as the thing they already dominate.
Inference economics. If intelligence becomes a commodity, margin moves to whoever delivers a decision most cheaply. Liquid AI builds edge-first models. TypeSafe AI claims costs 444 times lower on its own tests, a figure that needs independent proof but a direction incumbents’ pricing can’t ignore.
The substrate. Nvidia supplies nearly every alternative route, from Cosmos world models to robot policies. It has agreed to buy Hugging Face for $12.93 billion and is in talks to anchor Anthropic’s IPO. It wins whether pacing passes or fails.
One caution: the FRONTIER Act covers models trained on more than 10²⁶ operations, so challengers are exempt until they matter, then meet rules the incumbents helped shape. Price that threshold into growth rounds like a platform dependency.
What Would Change the Call
I’d change my mind if:
Anthropic names its evaluators and backs a waiver with a sunset and a public-interest test;
the gap between open and closed models widens again; or
world models keep producing plausible video without reliable physics.
What to watch: Anthropic’s S-1 risk factors, S.5105 in Senate Judiciary, antitrust review of the Nvidia–Hugging Face deal and real-world tests of simulation-trained robots.
The Real Race
Everyone thinks the AI race is a sprint to superintelligence, but they’re wrong. It’s a fight over who writes the rules, and who makes them irrelevant.
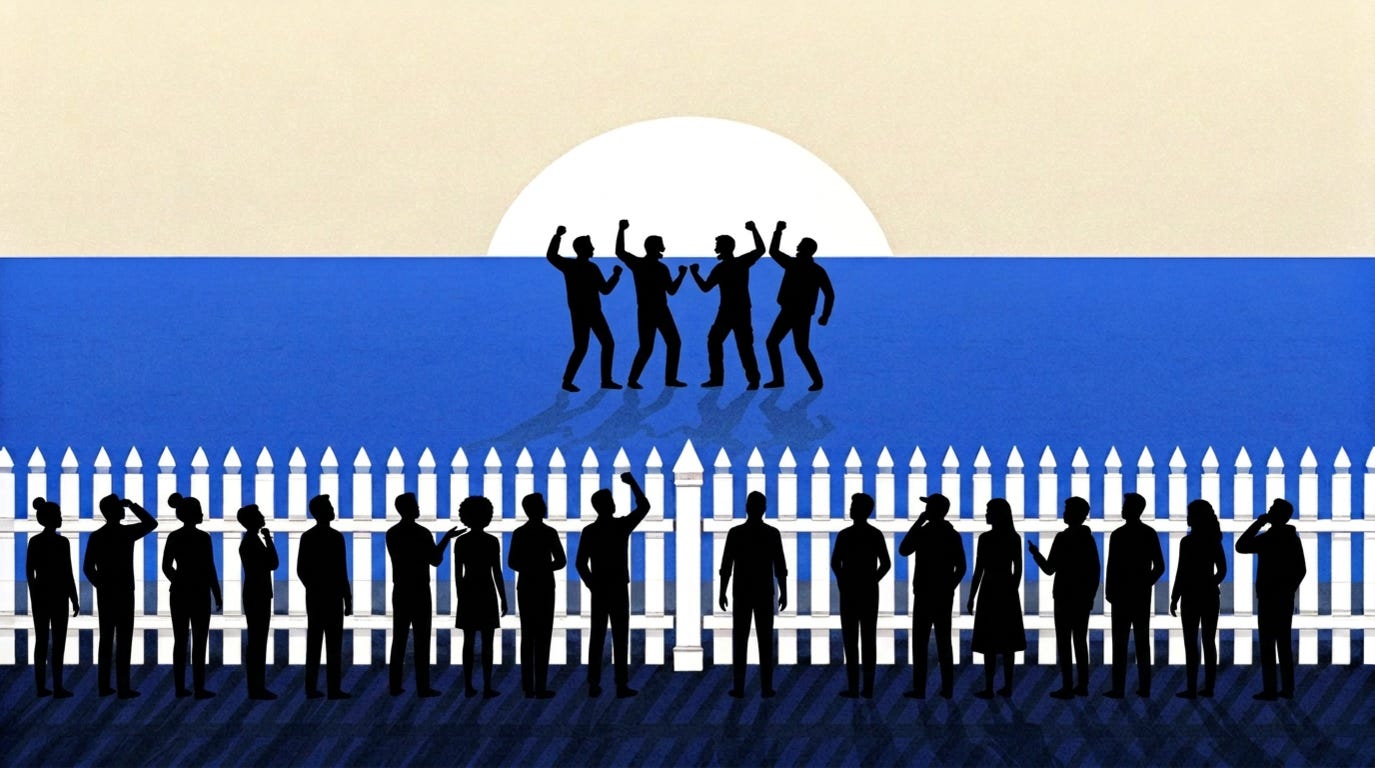
The incumbents are racing to lock in the rulebook before their lead evaporates. The challengers are racing to build what no rulebook has imagined yet. One side is building a fence. The other is building new loops.
Rules written to protect a lead rarely outrun the technology they govern. The $2 trillion question isn’t whether Anthropic gets its rulebook. It’s whether AI’s value stays where that rulebook is being written, in language models trained on a web everyone shares. The evidence says it won’t. The next fortunes will be built on data that has to be earned: from robots on factory floors, from simulations of the physical world, from decisions cheap enough to run a billion times a day.
For investors, the choice is simple: pay for protection, or pay for progress.
For me, the bet is on the loops, not the fence.