


The banking industry has spent the last year asking the wrong question when it comes to stablecoins.
The headline version goes like this: stablecoins could put $6.6 trillion in deposits at risk, lending could contract by a trillion dollars, and the payment system as we know it could be restructured. That framing has generated a year of congressional testimony, Fed research, and industry lobbying; organized almost entirely around balance sheets, around where the money sits.
The more consequential question is not whether deposits leave. It is whether the customer relationship leaves with them. Those are different risks, with different timelines and different remedies. And the second one is underpriced.
Where the number actually came from
The figure most often cited, $6.6 trillion in deposits “at risk”, comes from an April 2025 Treasury Borrowing Advisory Committee presentation. TBAC identified roughly $5.7 trillion in demand deposits and $0.9 trillion in other transactional balances as potentially exposed to stablecoin competition. Those balances were flagged because they already earn little or no interest, move easily, and increasingly live inside software rather than bank branches.
It is worth noting the slide was titled “Potential Deposit Types ‘At Risk’”, not Deposits That Will Leave. And scale argues against panic: Fed staff put the global stablecoin market at roughly $317 billion in April 2026, against some $12 trillion in outstanding U.S. bank loans. There is no credit crisis, only a funding mechanism worth understanding before one exists.
Whether those balances actually leave turns on one variable above all: will stablecoins pay yield?
The yield loophole, and what Circle is actually doing
The GENIUS Act bars issuers from paying interest directly to token holders. But the statute regulates the issuer, not affiliated distributors; and Circle’s business model shows how much room that leaves.
Circle’s revenue is the float: every USDC is backed by cash and short-term Treasuries, and Circle keeps the interest. Section 4(a)(11) says Circle cannot hand that income to token holders, so Circle hands it to distributors instead, passing through to Coinbase effectively all of the income on USDC held in Coinbase accounts. Coinbase returns part of it to users as “USDC Rewards.”
Follow the money and the structure is a money market fund that has outsourced its customer relationship. Circle keeps the float; Coinbase keeps the app, the customer, and the reason anyone holds the token at all. But the more revealing detail is what Circle’s cost structure concedes: the issuer doesn’t own the customer either. It pays cash for a relationship it cannot originate itself, the market price of the interface, quoted today.
Without yield, adoption depends on utility. With it, stablecoins stop competing only for transactions and begin competing for funding. That is not a product decision. It is a banking decision.
Three channels, and the obvious one matters least
Most discussions assume the rest of the story: money leaves banks, banks lose funding, banks make fewer loans. Federal Reserve staff identify three channels, and the direct one matters least.
One: deposits leave and never return. Balance sheets shrink, credit contracts, but only if reserves don’t recycle back into commercial banks.
Two: the deposits stay, but change character. Suppose a corporation converts $100 million from its operating account into stablecoins, and the issuer redeposits that $100 million as reserve backing. System-wide deposits have not moved by a dollar, yet the funding has changed completely. Operating deposits are diversified, relationship-driven, often insured. Reserve balances are concentrated, uninsured, and capable of moving at digital speed, demanding larger liquidity buffers and higher internal funding costs. The balance sheet is the same size; its quality is not, and long-duration lending gets harder to fund. Even the Council of Economic Advisers, far more optimistic overall, calls this composition shift the central mechanism.
Three: the reserves concentrate. They pool in a few custodial institutions whose business models prioritize liquidity over lending, shifting capacity away from the regional banks that finance much of the real economy.
Neither channel two nor channel three requires a dollar to leave the banking system. The damage, where there is any, is done by money that stays.
The numbers are scenarios, not forecasts
Fed research presents a sensitivity analysis: outcomes conditional on assumptions, not a prediction:
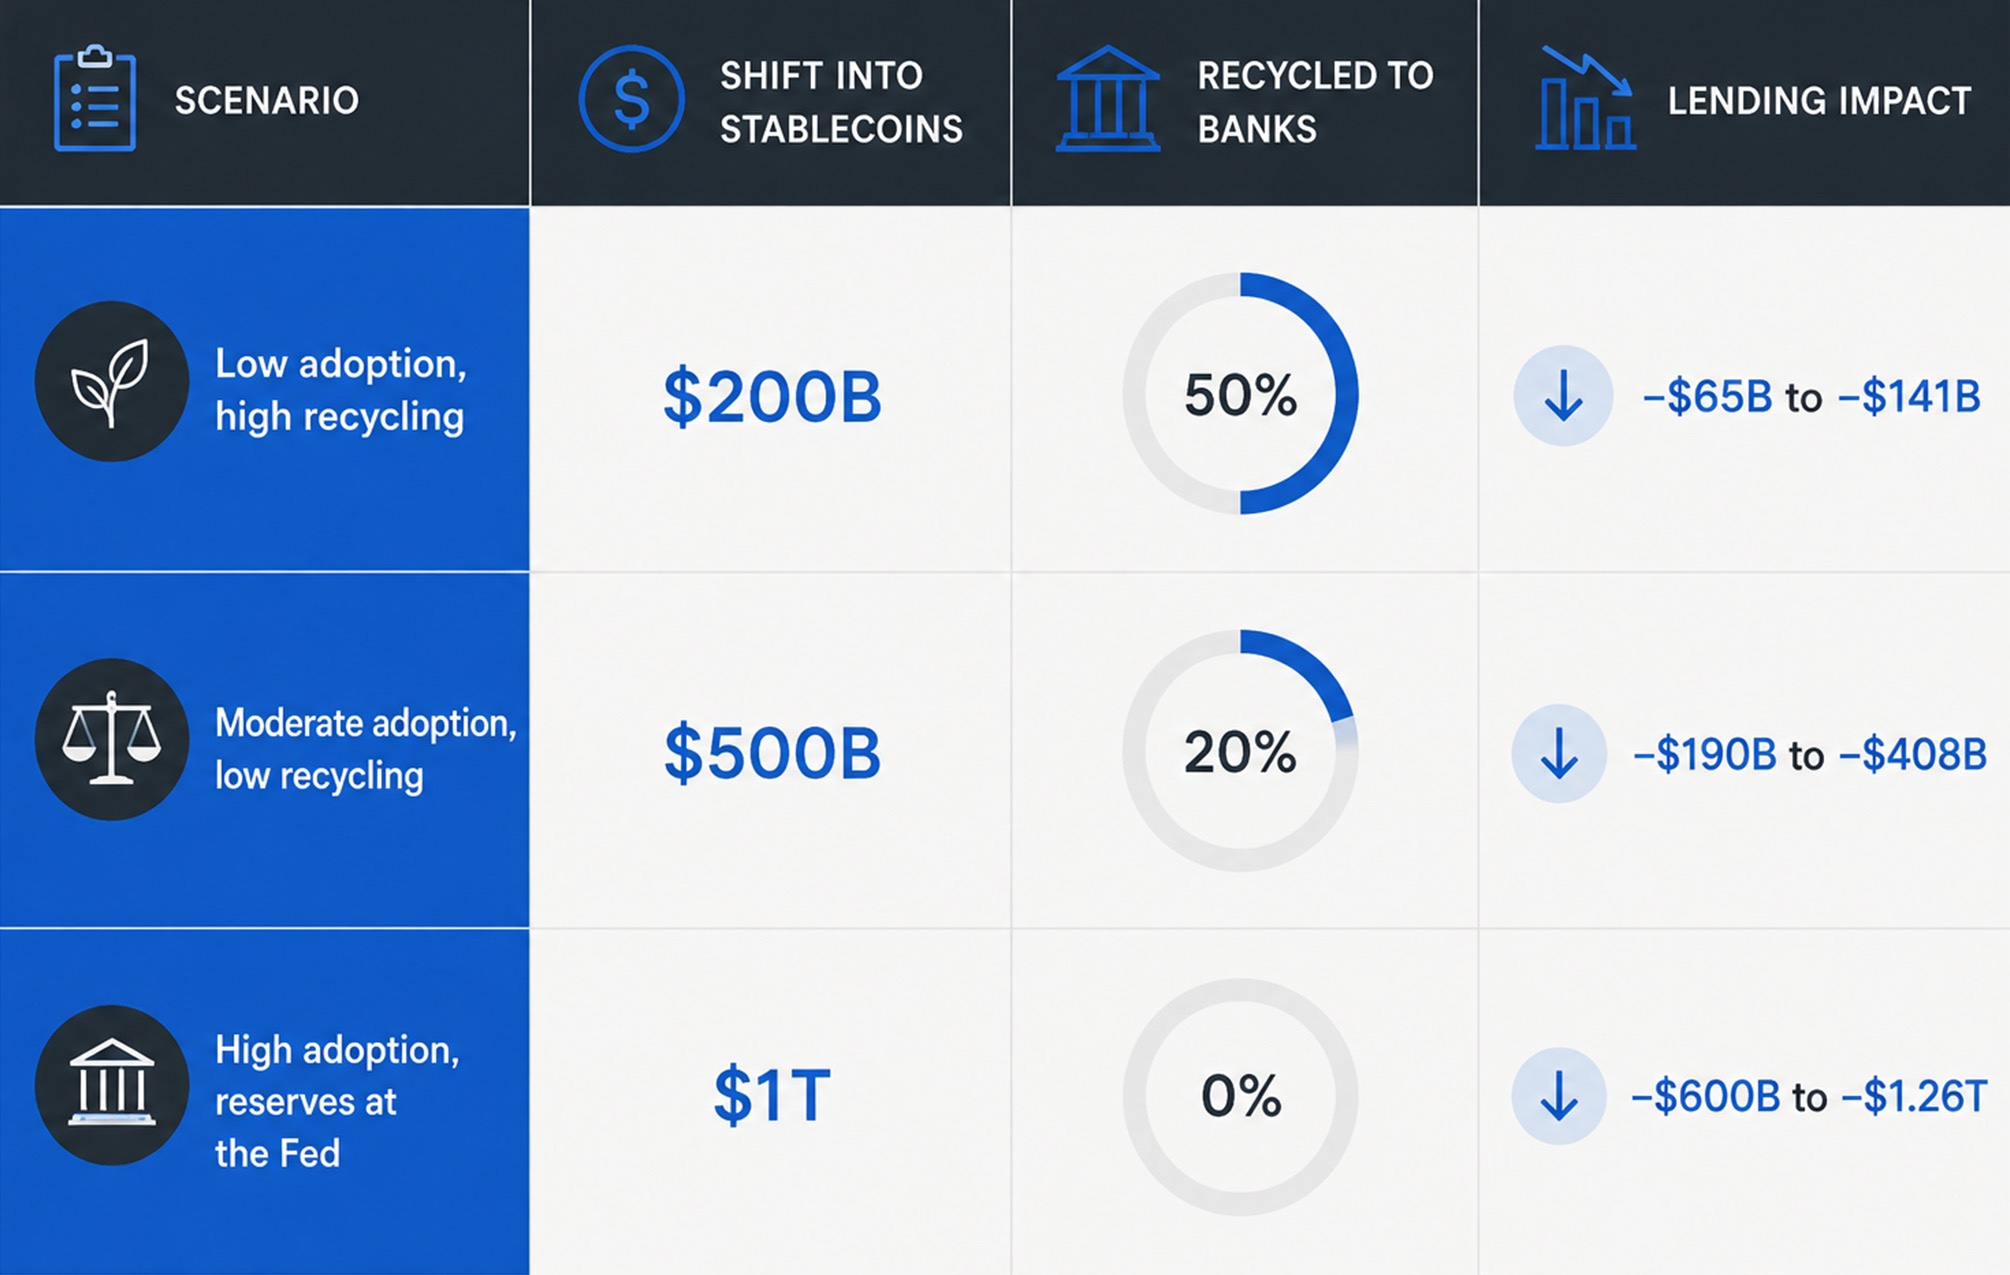
The column that matters is the third. Recycled means the issuer parks the dollars back as deposits at a commercial bank, the money left the customer’s checking account but is still available to fund loans. Not recycled means it sits where banks cannot lend against it: Treasury bills held outside the system, or balances at the Fed. That is when funding genuinely disappears. Adoption grows fivefold from the first row to the third; the damage grows roughly tenfold. Recycling, not growth, does most of the work.
Which is why serious people reach opposite conclusions from identical arithmetic. The Council of Economic Advisers assumes high recycling, and on those assumptions prohibiting stablecoin yield adds roughly $2.1 billion in lending 0.02% of outstanding U.S. loans, a rounding error. Fed staff run the same model with the assumptions relaxed and get figures three orders of magnitude larger.
Neither side has made an arithmetic error. They disagree about the recycling rate, and that rate is not a fact about technology. It depends on whether issuers gain Fed master accounts, whether yield reaches consumers, whether the Fed keeps ample reserves. Each is a decision someone will make in rulemaking. This debate is presented as a disagreement about technology. It is a disagreement about policy.
History says adapt, not panic
We have seen this pattern before. Money market funds looked existential because Regulation Q barred banks from paying competitive interest. When Congress changed the rules, banks launched money market deposit accounts and won back much of the lost funding. PayPal is the same story: banks fought it in lobbying and litigation, then beat it back with a better product: real-time payments, FedNow, Zelle.
Technology rarely destroys banking. It changes what customers expect from it. The question is not whether banks survive stablecoins. It’s what they become after they do.
The relationship is the real exposure
For generations, banks treated payments as a utility. But payments were never the business, they were how the business began. A checking account was valuable not because moving money was profitable, but because it was the front door to everything that followed: lending, treasury, payroll, wealth management, decades of customer data. The balance sheet was built behind it.
Stablecoins reverse that architecture. A bank-client relationship is not a legal claim on a deposit. It is an accumulation of four flows, and each one follows whoever owns the interface.
Data flow. Transaction flow is the raw material for underwriting, pricing, and cross-sell. A bank funding stablecoin reserves learns nothing about the businesses behind those tokens. The issuer and its distributors learn everything.
Attribution flow. When a business holds balances in a wallet inside its ERP system, the brand it associates with “where my money is” is the software vendor. The bank holding the reserves is invisible.
Origination flow. Lending opportunities surface where financial activity begins. If invoicing, payroll, and settlement all happen inside a platform, that platform sees the working-capital gap first. The bank stops discovering its own customers and starts bidding for referrals.
Switching cost. Deposit relationships are sticky because moving them is tedious. When the operational hub is software and the bank is an interchangeable back end, that friction protects the platform instead. The bank becomes the easiest component in the stack to replace.
Every payroll system that settles in stablecoins compounds the effect. Banks may go on financing relationships they no longer control. That is not disintermediation, it is something subtler. Banks are not becoming obsolete. They are becoming infrastructure.
The counterargument banks are already building
One assumption runs underneath all of this: that the bank is the counterparty and someone else is the issuer. That is the industry’s current posture, and it may not hold.
Nothing in the GENIUS Act stops a bank from tokenizing its own deposits, and several of the largest already have: JPMorgan’s deposit token through its Kinexys unit, Citi Token Services, various consortium settlement projects. A tokenized deposit moves at the speed of a stablecoin and settles inside the same software, but it remains a deposit: on the issuing bank’s balance sheet, inside the insurance perimeter, and legally free to pay interest, which a stablecoin is not. If the threat is programmable money, the bank version answers it without the composition problem in channel two and without needing a yield loophole.
The catch is the interface, again. Tokenized deposits are largely closed-loop, they work well inside one institution or consortium and poorly across the open networks where developers actually build. A treasurer who wants one balance that moves between counterparties, chains, and applications is not well served by ten incompatible bank tokens, and fixing that requires shared standards banks have historically been slow to build together.
So the sharper framing is not banks versus stablecoins. It is whether banks can put their own instrument where the customer already is, fast enough, and interoperably enough, to matter.
Two futures, one of them quiet
Those choices: where reserves land, whether yield reaches consumers, whether issuers gain Fed master accounts, determine which of two futures arrives. In the first, deposits drain and banks fight to replace funding. In the second, the money never moves: reserves sit in commercial banks, balance sheets hold their size, every headline metric looks fine, and the customer relationship migrates into software one integration at a time.
That second transition has no scenario table and no trillion-dollar estimate. Which is precisely why it is underpriced. A bank can measure deposits leaving. It cannot easily measure the customer who still banks with it but no longer thinks so.
Banking has never been only a balance-sheet business. It has always been a relationship business that happened to be built on a balance sheet. Stablecoins may not change where the deposits sit. They may change who customers believe they bank with.
